Mortgage financing can be  frustrating.

It doesn't have to be.

Here's our 3 step plan.
STEP ONE

Get in touch.

The best place to start is by letting us know who you are! Click the start here button below and you'll be directed to a page where you can complete an online application, schedule a meeting to discuss your financial situation, connect with us on the phone, or send us a quick message.
START HERE
STEP TWO

Walk through the process together.

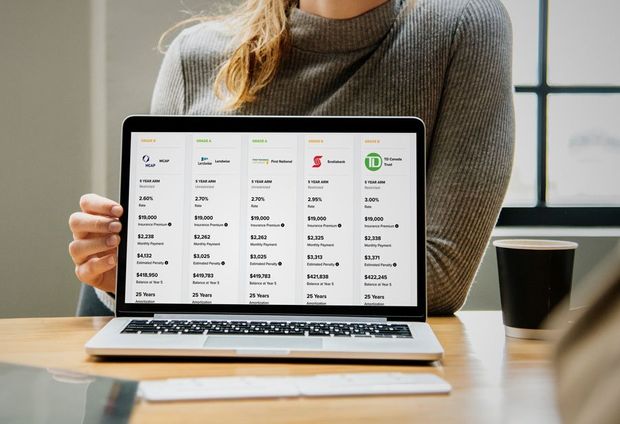
Our experienced staff have mastered the mortgage process. Let us guide you through getting the best mortgage product for you! In our online portal you'll be able to do the following:

  • Upload all of your documents in one place (paperless)
  • Add your real estate agent and lawyer (collaborating saves time)
  • Compare all mortgage types and features from different lenders
  • Customize the perfect mortgage to match your lifestyle
  • Make calculations based on different financial scenarios
  • Sign all documents online to complete your mortgage financing
START HERE
STEP THREE

Accountability moving forward.

The Canadian mortgage industry can change overnight. Don’t be surprised to get a call from one of our experts with updated options when things change. We continually work to save you money at every stage of your home ownership journey.


We're committed to ensuring you have the lowest overall cost of borrowing throughout the life of your mortgage! As long as you need a mortgage, we're here to help.

START HERE

Trusted by Our Clients 

With hundreds of 5-star reviews, our clients are at the heart of everything we do. Each review reflects the care, expertise, and commitment our team brings to making the mortgage process simple and stress-free.

From first-time buyers to seasoned homeowners, we’re proud to have built a reputation for trust, transparency, and results. Your stories inspire us—and we’re grateful for every client who takes the time to share their experience.

When you choose us, you’re not just getting a mortgage broker—you’re joining a community that puts people first.

Book Now

500+ Google reviews from indi clients

START HERE

Our Services

We have the right mortgage if you are...

  • BUYING YOUR FIRST HOME

    If you're looking to buy your first home, you've come to the right place. Our mortgage experts will simplify everything and guide you through the entire process. We're with you every step of the way! 


    Learn More >

  • BUYING YOUR NEXT HOME

    If you own a home, but you've got your eyes set on your next home, there's a lot to consider. We have the experience to ask the right questions and make sure you explore all your options before making your move! 


    Learn More >

  • REFINANCING YOUR MORTGAGE

    If you're looking to potentially access some of the equity you've built up in your home, we can help. There are many reasons to refinance; let us outline the best way to make that happen at the lowest cost to you! In fact, depending on your current mortgage, there's a possibility a mortgage refinance could save you money long term! 


    Learn More >

  • RENEWING YOUR MORTGAGE

    If your current mortgage term is within 6 months of being complete, we'd love to hear from you. Don't just sign your lender's renewal offer, you've got negotiating power, we'd love to negotiate on your behalf!  


    Learn More >

  • BUYING A CONDO

    If you're looking to buy a condo, you've come to the right place. Understanding condo documents and presenting them to a lender to secure mortgage financing can be difficult. Let our mortgage experts guide you through the process.


    Learn More > 

  • BUYING INVESTMENT PROPERTY

    There are many ways you can go about building a real estate investment portfolio. Having a clear plan is crucial. At Axiom, we understand the intricacies of financing investment property and would love to work with you. 


    Learn More >

  • SELF-EMPLOYED

    If you're self-employed or run your own business, chances are your income will be subject to heightened lender scrutiny when looking for a mortgage.  At Axiom, we know exactly how lenders look at self-employed income and will help build a plan to ensure you get the best financing available.


    Learn More >

  • GOING THROUGH A DIVORCE

    If you are working through your options as a recently separated or divorced person, we have access to mortgage products designed for you. Our mortgage experts know exactly how to help you through this difficult time. 


    Learn More >

START HERE

"I had a great experience working with indi."


"indi makes it a priority to ensure their clients are educated throughout the whole mortgage process. As a first time buyer it can be a confusing and overwhelming process – they were patient and helped me understand everything I needed to know and answered my questions."


Patricia Kopec
indi Mortgage homeowner since July 2016. 

Put our experience to work for you

Indi Mortgage has been helping Canadians achieve their home ownership and real estate investment goals since 2001. Welcome to our family.

MEET THE TEAM

We Support

University of Guelph Athletics

Home of the Guelph Gryphons. The University supports student-athletes, coaches, and fans across 17 different sports. Promoting physical education through structured competitive environments helps the next generation gain a clear advantage.
Junior Gryphons Minor Sports

The Junior Gryphons are over 6000 children, and 68 rep teams across 5 different sports in our community. Children as young as 3 start participating in team activities, building social skills, and making friends.
Children's Foundation

The Children’s Foundation empowers children and youth by connecting families with opportunities to build hope for lifelong change and break the cycle of poverty. Over 1,000 volunteers work with the Foundation to make our neighborhoods that much brighter.

YOU make it possible for us to support these organizations!

THANK YOU!

Resources to keep you learning

Sharing knowledge and empowering Canadians is in our DNA. Our blog is filled with tips, tricks and expert advice that can help you save thousands.
By Champion • October 7, 2026
If the title of this article caught your attention, chances are your family is growing. Congratulations. If you’re thinking now is the right time to move into a home that better fits your growing family—but you’re unsure how parental leave affects your ability to qualify for a mortgage—you’re in the right place. Here’s the good news. Qualifying for a mortgage while on parental leave is possible when it’s done correctly. When you work with an independent mortgage professional, lenders can often qualify you based on your return-to-work income , as long as you can provide documentation confirming you have guaranteed employment waiting for you. A word of caution If you walk into a bank branch and disclose that you’re currently on parental leave, there’s a chance the bank will only allow you to qualify using your parental leave income. That can significantly reduce your borrowing power. Parental leave income is typically limited to 55% of your previous earnings, up to a weekly maximum. Qualifying on that amount alone can restrict your options and impact the type of home you can purchase. Why lender choice matters One of the biggest advantages of working with an independent mortgage professional is choice . You’re not limited to one lender’s rules or products. Some lenders will allow you to qualify using 100% of your confirmed return-to-work income , which can make a meaningful difference in your approval amount and overall options. What you’ll need to qualify Most lenders will require an employment letter that includes: Employer name (preferably on company letterhead) Your job title Original start date (to confirm probation has been completed) Confirmed return-to-work date Guaranteed salary upon return Lenders want reassurance that your income will resume once parental leave ends. You may also be asked to provide income history from the past couple of years, which is standard for most mortgage applications. One important note Whether or not you actually return to work after parental leave is entirely your decision. From a mortgage perspective, qualification is based on having a confirmed position available to you at the time of approval. If you have questions about qualifying for a mortgage while on parental leave—or anything mortgage-related—please connect anytime. I’d be happy to walk you through your options and help you plan with confidence.
By Champion • September 30, 2026
You’ve outgrown your current home. It no longer fits your life, so moving makes sense. And you’re not interested in juggling two properties. Selling first and buying something new feels like the right move. Ideally, you want possession of the new home before leaving the old one. That overlap makes moving easier, reduces stress, and gives you time to paint, renovate, or settle in before the boxes arrive. But there’s a common challenge. What if the down payment for your next home is tied up in the equity of the one you’re selling? That’s where bridge financing comes in. How bridge financing works Bridge financing temporarily unlocks equity from your current home once it has a firm sale . It bridges the gap between selling your existing property and purchasing your next one, allowing you to use that equity toward your down payment. What about competitive markets? In a hot market, a strong offer often means a larger deposit . If you don’t have that cash sitting in your account, but you do have equity, a deposit loan can help you compete with confidence. The non-negotiable requirement To qualify for bridge financing or a deposit loan, your current home must have a firm, unconditional sale . No firm sale = no bridge or deposit loan. Lenders need certainty to calculate available equity and manage risk. Bottom line A firm sale is the key that unlocks bridge financing and deposit loans. If you’re planning a move and want to understand how these options could work for you, let’s talk. I’m always happy to walk you through your options and help you plan your next step with confidence.
By Champion • September 23, 2026
Financial setbacks happen. Bankruptcies and consumer proposals are more common than most people realize—and they don’t define your future. Going through one doesn’t mean homeownership is off the table forever. It simply means lenders want to see that you’ve taken control, learned from the past, and built a stronger financial foundation moving forward. What lenders look at after a bankruptcy or consumer proposal How long it’s been since your discharge Your discharge date matters. For lenders, this is your reset point. There’s no law that says you must wait a specific amount of time before applying for a mortgage, but the longer your track record after discharge, the stronger your application becomes. What matters most is how responsibly you’ve managed your finances since then. Your credit rebuild Re-establishing credit is critical. After discharge, most people start with a secured credit card and use it consistently and responsibly. To be considered fully re-established, lenders typically want to see: Two active trade lines At least two years of clean payment history Credit limits of around $2,500 on each No late or missed payments Your down payment or equity The more money you can put down—or the more equity you have when refinancing—the lower the risk for the lender. A stronger down payment often opens the door to better terms and more lender options. Your debt service ratios Lenders will also look closely at how much of your income goes toward housing and other debts. The stronger your income relative to your monthly obligations, the easier it is to qualify. Conventional vs. insured mortgage options To access the most competitive mortgage products, lenders typically want to see: At least two years plus one day since discharge Fully re-established credit Minimum down payment requirements met Mortgage insurance in place if your down payment is under 20% (through CMHC, Sagen, or Canada Guaranty) Total debt obligations generally not exceeding 44% of your gross income Alternative lending options Not every situation fits neatly into a bank’s box—and that’s where alternative lending can help. Independent mortgage professionals work with both traditional and alternative lenders, including those who specialize in complex financial situations. These lenders look at the full picture: equity, income stability, and your plan moving forward. While rates and terms may not be as competitive as prime lending, alternative financing can be an effective short-term solution—especially if you need a mortgage before your credit is fully rebuilt. Let’s talk about your next step Whether you’re planning ahead for the best possible mortgage—or need a solution sooner rather than later—there are options available. If you’d like help mapping out a clear path forward, reach out anytime. I’d be happy to review your situation and help you build a plan that gets you back into homeownership with confidence.

Our Monthly Newsletter Can Save You Thousands

Contact Us

Getting Started?

The best place to start the mortgage process is by completing an online application. There are no fees or commitment to do this. Once we have your application, we'll be in touch!

START HERE

Make some calculations

If you'd like to run a few calculations before getting started, we'd love to help you. First tell us where you are in your journey to buying a home

I'm just getting started

Exciting times!  Let's find out how much you'll be able to afford once you decide to buy.

CALCULATE

I have a home in mind

Great! Let's find out whether you'll be able to afford to buy it!

CALCULATE

I want to refinance my home.

No problem! Let's find out how much you could take out.

CALCULATE

Looking for a quick answer?

If you'd rather send a quick note to get the process started, go ahead, we'd love to hear from you. 

Contact Us

Schedule a meeting.

While the best way to get in touch with us is through the online application, if you'd prefer to talk with someone, we're accessible to you!

BOOK NOW